Today, Europe launched another stinker of a bugbear.
This time it is Italy. The PM has called it quits. The economy is fast stalling and the government may not be able to be liquid enough to pay its impending debts. So, bond prices in Italy went beyond the so-called unsustainable 7% level.
Pandemonium struck again at most global markets erasing recent gains as fears abound about the potential break up of the Euro currency market.
Bursa KL is also not spared, losing 17 points currently.
For Digi, it is as good a time to take that much needed rest.
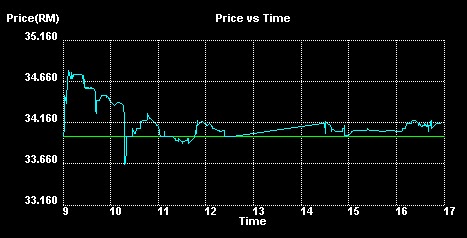
Falling to RM33.90 at one point, Digi is now trading in crimson waters just above the RM34.00 level.
The likelihood is Digi will end in red waters. And so it did, at RM34.00 for a 16 sen loss.
November 10, 2011
November 09, 2011
Wilmar Rides the Storm
Wilmar International (Wilmar) is confident that higher prices will support its palm oil and sugar businesses though it underperformed missing earnings expectations. However, there is solace-net profit jumped almost 24 per cent jump compared to the earlier year.
Moreover,Wilmar’s lower-than-expected earnings were linked to a foreign exchange loss and weaker margins from its consumer product business as the rise in cost of feedstock outpaced the price increase.
Interestingly, Wilmar’s results compared favourably when benchmarked to world giants such as Cargill and Bunge with the former losing some 66 per centof its earnings of US agribusiness.
Bunge, the world’s largest oilseed processor and among the top sugar and ethanol producers,saw its earnings declined by a third.
Wilmar remains positive of its prospects, despite uncertainties in the global economy, due to the resilience in the demand for agricultural commodities and the continued growth of Asian economies as palm and laurics will benefit from the recent changes in the Indonesian export duty structure for palm products, which it said is highly advantageous for downstream processing margins.
The company has about one third of its total crude palm oil (CPO) refining capacity in Indonesia, Macquarie said in a research note, adding current CPO price could give Wilmar a potential uplift of US$104 (RM324) per tonne in Indonesian refining margins.
The world’s largest listed palm oil plantation firm, which generated more than half of its revenue from China, partly benefited from an increase in its cooking oil selling price by 5 per cent in China earlier this year.
Wilmar did caution that consumer product margins in the third quarter were still lower from a year earlier due to bigger increase in cost of edible oils feedstock, while the group had only about one month of price increase benefit in China. Wilmar was allowed to increase its price for consumer products in China on August 1.
The company, which owns palm oil plantations in Indonesia and Malaysia as well as sugar operations in Australia, earned a net profit of US$321.05 million for the quarter ended September 30, compared to US$259.5 million earned a year ago. That compares to an average forecast of US$461 million from five analysts.
Excluding the exceptional items, the company recorded a net profit of US$442.4 million compared to US$172.4 million a year ago.
Its earnings in the second half of 2010 were hit by losses from its oilseeds and grains business, which the company blamed on weak margins and inopportune buying.
Wilmar’s share price has declined by 0.7 per cent since the start of this year, compared to 10 per cent fall in the broader Singapore market.
So, will PPB see more dividends from Wilmar this year?
Labels:
Stocks
November 08, 2011
D-Day Digi to Go Ex
Was there a push or was it a genuine buyer at RM34.80? That we may never know for sure.
What I saw in the morning session before the EGM scheduled at 2 pm is that buying pressure has receded and bargain hunters are stacking up; pulling prices down. Most stock were done in the RM34.60-RM34.70 price range.
By 11 am, the price of the stock has dipped below RM34.00 for the second time falling as much as 34 sen at once instance.
Now it is just playing limbo rock below the RM34.00 price level and sitting at the price plateau of RM34.00 and some occasional price spurts has brought it to positive territory.
Let us see how it will settle down at the 12.30 trading break.
Looking back,it can be seen that confidence in the stock stayed at an upbeat bias as the stock transcended the psychological RM34.00 mark. Subsequently it see-sawed between RM34.04 and RM34.16 finishing at at RM34.16 for another 16 sen gain. Paltry but significant as the stock has now been approved for splitting.
Ass the time-table goes, the share will go ex on 21 November. Those shareholders who are on the company's register at 5 pm on 23 November will get the divided shares into their respective CDS by day-end.
After that, it will be dependent on market forces and perception of the historical RM0.01 sen share may give Digi a brand new image at the single ringgit league once more.
Let's look forward to Thursday 24 November 2011.
Labels:
Stocks
Hitting RM34
Somehow I have a gut feeling that someone is benchmarking the stock price of Digi before the split.
Some stock analyst had forecasted that Digi will go ex at RM3.40. So true to form, it burst the banks and headed beyond to RM34.22; pulling back comfortably to perched at RM34.00 at the day's close. As far as the mission is concerned, they did their job pretty well as the price breached RM34.00.
Anything more will be on its own steam.
Tomorrow, at the EGM, the share will officially be endorsed for a share split from its current 10 sen par to become a 1 sen par share. Theoretically, based on today's price, the price of RM3.40 per share brings a honourable premium of RM3.39 sen.
So let us see the price trajectory of this counter until Digi ex-split at the end of November.
Fantastic!
Labels:
Stocks
YTL Corp-Excitingly mischievous
On the GLC-Non GLC divide, one company continue to up-end almost everyone.
Perhaps Robert Kuok'e empire rule supreme. Perhaps Genting Highland Group is a formidable adversary.
But right there before our very eyes-there is the looming YTL Group helmed by the founder and his financially savvy son.

I was just looking at the reserves and cash in hand of YTL in their latest Annual report 2011 posted on Bursa KL's website this morning.
What I found interesting is that the reserves have been rising rapidly even more dramatic than the current flood waters in Bangkok.
Up to mid-2011,the fixed deposit of YTL has risen by another RM971 million since 2010. Extrapolating forward, before the year is out, additional fixed deposit should have crossed the RM1.2 billion mark by then
Combining deposit and cash in hand and bank balance, the total amount at the disposal of YTL stands close to RM12.24 billion as at mid 2011; and that my friend, is plenty of mucho dinero.
So what does a cash rich company do? Waste it as inflation devour its value? No, besides hedging it against currencies and other investment such as gold , it must do sometime about the cash horde.
As the say, an idle cash horde is a devil's playground and so good old Francis is watching out on how to make more money and more money.
What do you think he can do?
Well, for one-he is waiting for the green-light to build the KL-Singapore high speed train. Then there is always the next phase for his 4G telephony trajectory. As YTL Corp has sold most of its real estate to STAREIT or to YTL Land and Development, it is now a plenary company for strategic takeovers and tactical pursuits.
In the meanwhile,since its Treasury share accumulation is closing to the 7% mark, it may just distribute the shares generously to its loyal shareholders and start accumulating again once they obtain the renewal from its shareholders on 29 November.
The current share price is RM1.50- about the same price when it share split from 1 to 5 shares.
All in all, YTL Corp is proving to be one interesting company to watch.
Labels:
Stocks
November 03, 2011
Digi Goes North
Today is Friday but European markets looks bright and so it should have some positive effects on Asian markets.
As it goes Digi and Genting took top marks.
From a beginning low of RM32.60, Digi shares, though traded in small tranches, move up steadily after getting traction above RM32.70.
By lunch close, it has added a delightful 68 sen to RM33.16.
Whether it will remain so until the end of trading day is anybody guess.
I will post again at trading's end.
Yes, Digi finished off best but tacked on a handsome 82 sen to finished at RM33.30.
Looks firm this time though there was a spurt to RM33.48 at one point before it pulled back.
Labels:
Stocks
November 02, 2011
Dogmatic Digi?
Digi.Com is an interesting counter of late.
Have you watch the nature of its trading for the last ten trading days? Mighty interesting as if big boys are manipulating this counter for some unforseen reason. Real big bucks have been expended to push the counter up and then to leave it fall plumbline at trading’s end.
Digi is an occasional counter, seasonal spurts and falls but mostly getting price traction as time moves on. It is definitely investor-grade stock though day traders could pun it to advantage.
From RM31.00, it has moved surreptiously up the price ladder. Reaching mid-price of RM31.60, it started an erratic pattern-shooting up to RM33.50 only to fell flat and into red territory on the screen.
From 2rd November and today (3rd November), Digi prices have been better bucking the trend in spite of the soft market brought about by the Greek sycophants and their debt problem. Yesterday, it took in a gain of 40 sen to close at RM32.30 while today it posted a 18 sen gain to RM32.48.
Let us watch how this counter will perform until Digi’s EGM on 9 November. Will it heave-ho away tsunami-style or will it take on an incremental softer paced upward price movement?
Also, after price ex-all via its subdivision to 10 shares per share of 1 sen each, will it attract top feeders to move up vigorously at the single dollar level to convert into ardent longer term investors of this supposedly well managed company?
Let us observe the possible trajectory; the spurts, spills, rise and fall, won’t we?
Labels:
Stocks
Subscribe to:
Posts (Atom)